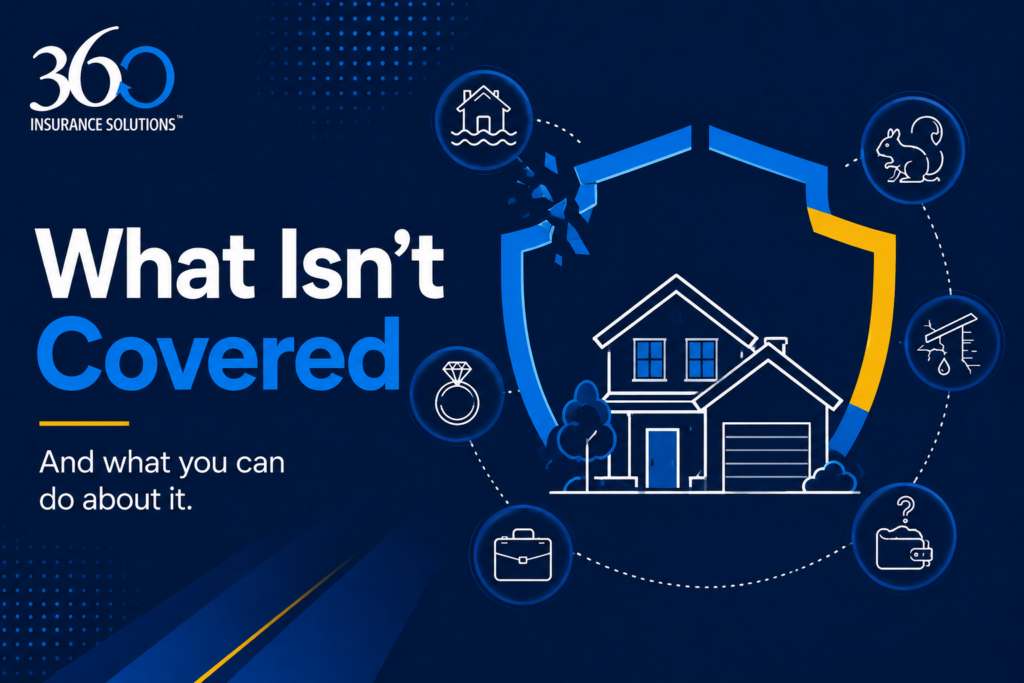
What isn’t covered – and what you can do about it.
“What’s covered” is the question everyone asks. “What’s not covered” is the one that actually matters, because that’s where people get surprised. Here are the exclusions worth knowing about, and more importantly, what actually fixes each one.
Fixable on This Policy
Jewelry and other valuables. Almost every policy caps how much it pays out for jewelry, and it’s usually far below what a real piece is worth. If you’ve got a ring, a watch, or anything else with real value, get it scheduled individually. This is one of the easiest gaps to close, and it’s one we bring up with clients often.
Accidental damage to your belongings. TV falls off the wall, laptop gets dropped, bike gets crushed under something. Whether this is covered comes down to your policy form. A Named Perils policy won’t cover it. Open Perils (sometimes called Special Coverage) might, depending on your deductible and the specifics. Worth knowing which one you actually have.
Sewer and water backup. This one’s not automatically included on most policies, which is exactly why we recommend adding it for our clients. It’s inexpensive, and it’s one of the more common claims we see people wish they had.
These Need an Entirely Different Policy
Flood. This is usually one of the first exclusions people notice when they read their paperwork. A flood is water coming off, or through, the surface of the ground, which is different from a pipe bursting inside your home. Standard homeowners insurance doesn’t touch this at all. Flood coverage comes from a separate policy entirely, either through the NFIP or the private flood market.
Earth movement. Earthquakes and mudslides fall here too. Most standard policies exclude this outright, but it can often be bought back through a separate endorsement or its own policy.
Home-based business. If you run a business out of your home, your business inventory and supplies are often limited or excluded entirely under a standard policy. If you’re using a detached structure, like a shed or garage, to store business equipment, that structure may not have coverage either. This needs an actual business policy, not an add-on to your homeowners.
Gig income on personal items. Play music for money on weekends, shoot photos for clients, that kind of thing? A lot of policies stop covering an item the moment it starts generating income. Your guitar or camera may need to move onto a business or specialty policy once you’re getting paid to use it.
No Insurance Fix, Just Good Upkeep
Vermin and pests. Squirrels and other critters chewing through siding, ductwork, and wiring, plus the mess they leave behind, isn’t covered on most policies. This one comes down to keeping your home sealed up and staying ahead of it, not insurance.
Slow, ongoing damage. Water stains, wood rot, a gutter that’s been hanging for months. If it happened gradually, insurance generally won’t step in. Regular upkeep is the only real defense here.Lost or misplaced items. Left your laptop at the airport and it never turned up? That’s not a covered loss. Theft is one thing, simply losing something is another, and most policies draw that line clearly.
The Bottom Line
A lot of what’s excluded actually has a fix, either on your current policy or through a separate one entirely. The rest just comes down to keeping up with your home. Knowing which bucket something falls into is the difference between a real gap and a surprise.